
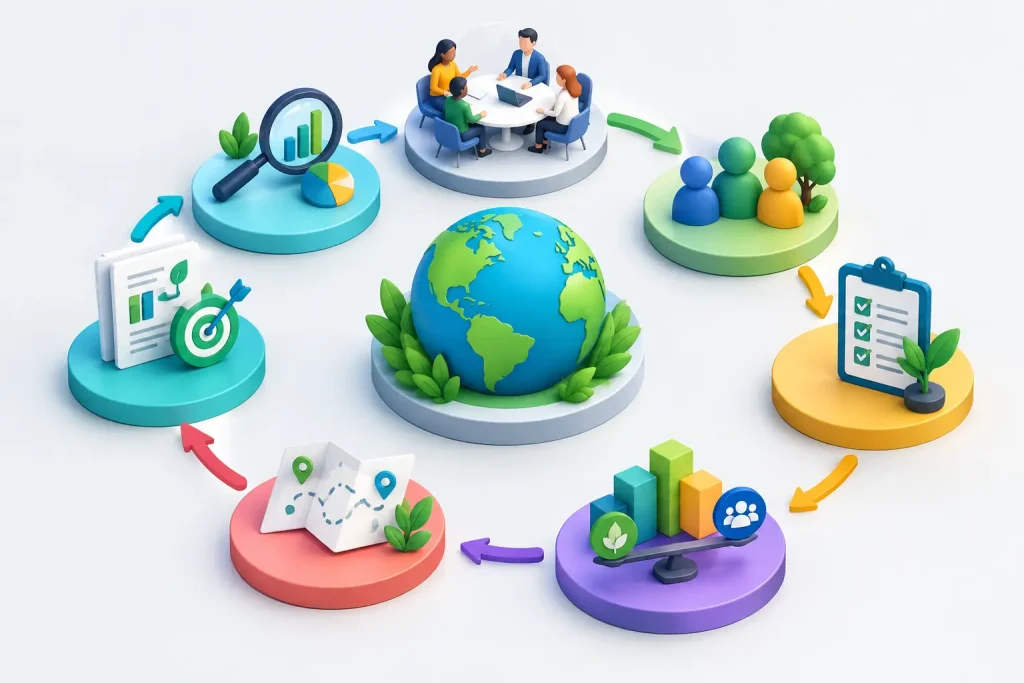
A materiality assessment is where ESG stops being a broad set of good intentions and starts becoming a business decision. A well-run ESG materiality assessment process helps leaders determine which environmental, social, and governance issues most affect enterprise value, stakeholder trust, operational continuity, and long-term growth. It prevents teams from spending resources on disconnected initiatives while critical risks and opportunities remain unmanaged.
For businesses operating across Malaysia and Southeast Asia, the pressure is practical. Customers, investors, supply-chain partners, employees, lenders, and regulators increasingly expect credible ESG action. The answer is not to report on every possible topic. It is to identify what matters most to your organization, explain why it matters, and build those priorities into strategy and operations.
What an ESG Materiality Assessment Is Designed to Do
Materiality is the discipline of prioritization. It gives an organization a defensible basis for deciding which ESG topics require leadership attention, targets, investment, governance, and disclosure.
A financial materiality lens asks how sustainability issues may affect the company. For example, energy price volatility, labor shortages, weak supplier controls, or poor data governance can affect revenue, costs, financing, and resilience. An impact materiality lens asks how the company affects people and the environment, such as through emissions, workplace practices, waste, community relationships, or product impacts.
Many organizations now consider both perspectives, often referred to as double materiality. The right approach depends on your reporting obligations, industry, stakeholder expectations, and business maturity. A growing business may begin with a focused assessment that establishes its ESG foundation. A larger company preparing for assurance or formal reporting may need deeper evidence, broader stakeholder input, and more documented controls.
The output should be more than a materiality matrix. It should be a decision tool that connects material topics to business owners, risk management, performance indicators, implementation plans, and reporting priorities.
7 Steps in the ESG Materiality Assessment Process
1. Establish the purpose, scope, and decision context
Start by defining what the assessment needs to achieve. Is the organization preparing an ESG report, responding to customer requirements, developing a sustainability strategy, improving risk management, or setting priorities for a transformation program? The purpose shapes the depth of research, the stakeholder groups to include, and the standard of evidence required.
Set the organizational boundary early. Consider subsidiaries, operating locations, joint ventures, supply-chain activities, and product life cycles where relevant. A manufacturer, for example, may find that supplier labor practices and purchased materials are more material than office waste. A services company may place greater weight on data privacy, workforce development, business ethics, and energy use.
This stage should also establish executive sponsorship. Without clear ownership from leadership, the assessment can become a communications exercise rather than a management tool.
2. Build a long list of relevant ESG topics
Create an initial universe of potential topics using recognized reporting frameworks, sector guidance, peer disclosures, enterprise risk registers, customer questionnaires, legal requirements, and internal strategy documents. The list should reflect the organization’s actual operating model rather than a generic ESG checklist.
Common environmental topics include energy, greenhouse gas emissions, water, waste, pollution prevention, climate resilience, and circular resource use. Social topics may include health and safety, employee engagement, diversity, human rights, responsible sourcing, customer welfare, and community impact. Governance topics often include board oversight, ethics, anti-corruption, cybersecurity, data privacy, tax transparency, and regulatory compliance.
At this point, do not try to decide what is material. The aim is to create a credible starting point that avoids blind spots. A topic that appears minor internally may be highly significant to customers, local communities, or investors.
3. Map stakeholders and gather meaningful input
Materiality cannot be determined solely in a boardroom. Stakeholder engagement tests internal assumptions against the people affected by, or able to influence, the business.
Identify priority stakeholder groups based on their relationship to the company and the relevance of their perspective. This may include employees, customers, suppliers, investors, lenders, regulators, local communities, industry bodies, and senior leadership. Not every group needs the same engagement method. Interviews may be appropriate for executives and key customers, while surveys, workshops, supplier assessments, and existing feedback channels can provide useful input elsewhere.
The quality of questions matters. Ask stakeholders to assess the significance of topics and explain their concerns, expectations, or observed impacts. Avoid asking only whether they “care” about ESG. Almost everyone does. The useful insight is why a topic matters, where the organization is exposed, and what action stakeholders expect.
4. Assess impacts, risks, and opportunities with evidence
This is the analytical core of the process. For each topic, evaluate the scale and likelihood of business impacts, as well as the company’s impact on people and the environment. Use available evidence: incident records, audit findings, energy and waste data, employee turnover, customer feedback, supplier performance, legal developments, insurance information, and financial forecasts.
A simple scoring model can help create consistency. For business relevance, consider potential financial effect, time horizon, likelihood, and ability to influence the issue. For impact relevance, consider severity, scale, whether impacts can be remedied, and likelihood. Document the rationale for each score. A score without an explanation is difficult to defend when leadership, auditors, or stakeholders ask how priorities were determined.
Judgment is unavoidable, especially where data is incomplete. The goal is not false precision. It is a transparent, repeatable process that uses the best information available and identifies gaps that require further work.
5. Prioritize topics and challenge the results
Use the analysis to rank topics and identify those that cross the organization’s materiality threshold. A matrix can communicate the results clearly, but it should not be treated as the final decision. Review the proposed priorities with cross-functional leaders from operations, finance, human resources, procurement, legal, risk, and commercial teams.
This review often reveals useful trade-offs. A topic may rank highly with external stakeholders but have limited internal data, requiring a phased response. Another topic may present a significant financial risk but receive little stakeholder attention, meaning it still needs strong management. Prioritization is not a popularity contest. It is a decision about where the organization must act, monitor, disclose, or improve.
The final list should be focused enough to guide investment. If every topic is labeled material, the organization has not truly prioritized.
6. Convert priorities into strategy and operational action
A materiality assessment creates value only when it changes decisions. Assign executive accountability and operational owners for each material topic. Define the relevant policies, controls, targets, data requirements, capital needs, and performance indicators.
For example, if energy and emissions are material, the next step may be an energy baseline, equipment efficiency review, renewable-energy feasibility study, and emissions-reduction roadmap. If responsible sourcing is material, procurement criteria, supplier due diligence, contract clauses, and supplier capability-building may be required. If governance is a priority, the organization may need clearer board oversight, whistleblowing procedures, anti-bribery training, or stronger data controls.
This is where ESG becomes a source of commercial value. Better resource efficiency can reduce costs. Stronger supplier practices can protect continuity. Better workforce conditions can support retention and productivity. Governance discipline can reduce exposure and improve confidence among customers, investors, and partners.
7. Validate, disclose, and refresh the assessment
Document the methodology, stakeholders consulted, scoring criteria, evidence sources, governance decisions, and final material topics. This record supports credible reporting and gives the organization a baseline for future improvement.
Communicate the results in a way that is proportionate to your audience. Leadership needs clear decisions and accountabilities. Employees need to understand how priorities affect daily work. External stakeholders need transparent, balanced disclosure that explains both progress and remaining gaps.
Materiality should be reviewed regularly, typically annually or when a significant change occurs. An acquisition, new market, supply-chain disruption, regulatory development, major incident, or shift in customer expectations can change what is material. Treat the assessment as a living management process, not a one-time report requirement.
Common Mistakes That Weaken Materiality Assessments
The most common mistake is starting with disclosure rather than strategy. Reporting frameworks are useful, but copying a list of topics does not reveal what is most significant for your business. Another is relying only on senior management views. Leaders bring essential perspective, yet employee, customer, supplier, and community input may reveal issues that internal teams underestimate.
Organizations also weaken the process when they collect stakeholder feedback but cannot show how it influenced decisions. Close the loop by connecting findings to priorities, actions, targets, and governance. Finally, avoid creating ESG commitments that the business cannot measure or implement. A smaller set of meaningful commitments is more credible than a long list of aspirational statements.
Build Materiality Into Business Transformation
The strongest ESG programs treat materiality as the starting point for continuous improvement. The results should inform strategic planning, operational design, risk controls, workforce development, supplier engagement, and investment decisions.
Adcellent Biz helps organizations move from ESG awareness and assessment to practical implementation through a structured pathway that connects responsible business practices with measurable transformation. The right next step is to bring your leadership team together, test your assumptions against evidence, and choose the few ESG priorities that will genuinely strengthen your business for the years ahead.