
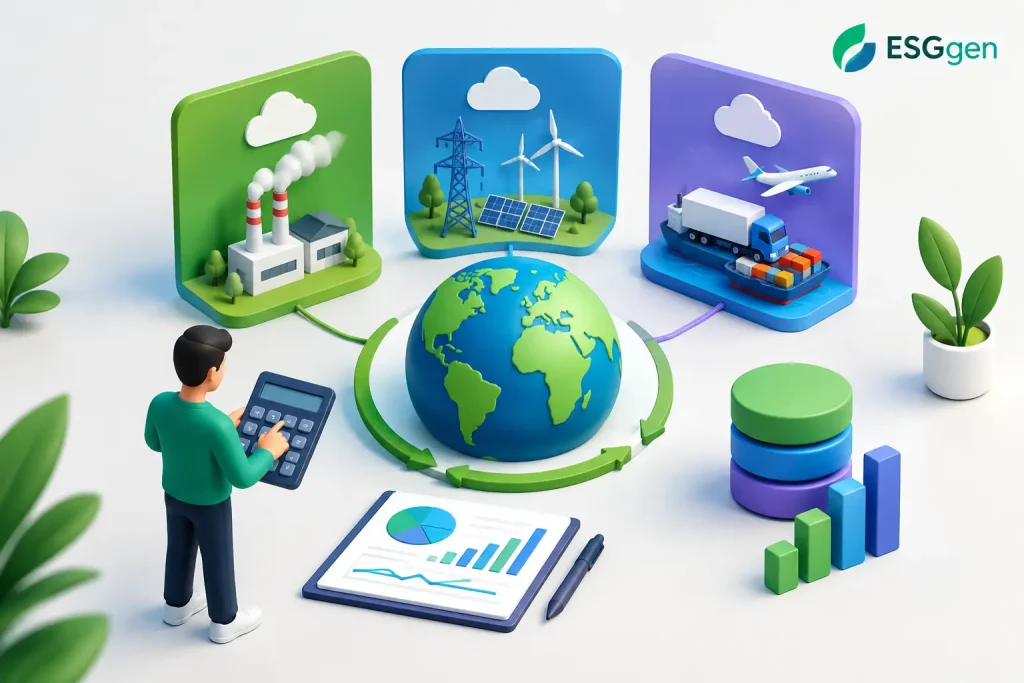
A utility bill, fuel receipt, and supplier invoice may look like ordinary operating records. Together, they can reveal where your business spends energy, depends on carbon-intensive inputs, and faces future cost or customer pressure. Learning how to calculate scope emissions turns those records into decision-ready information, not just another reporting exercise.
For founders and business leaders, the objective is not to produce a perfect footprint on the first attempt. It is to create a credible baseline, understand the largest sources of emissions, and build a process that improves as your data and capabilities mature. Done well, emissions calculation can support lower operating costs, stronger customer confidence, more disciplined procurement, and a more resilient growth strategy.
Start with the right emissions boundary
Before collecting numbers, decide what part of the organization the inventory covers. This is your organizational boundary. A company may account for facilities and assets it owns, or for operations it financially or operationally controls. The approach should reflect how the business is managed and remain consistent year to year.
Then set an operational boundary by separating emissions into Scope 1, Scope 2, and Scope 3. This classification prevents double counting within your own inventory and gives management a practical view of where action is possible.
Scope 1 covers direct emissions from sources your organization owns or controls. Examples include fuel burned in company vehicles, diesel generators, boilers, furnaces, and refrigerant leaks from air-conditioning or refrigeration equipment.
Scope 2 covers indirect emissions from purchased energy, usually electricity. It may also include purchased steam, heat, or cooling where relevant. Although the emissions happen at the power plant, your organization drives the demand by using that energy.
Scope 3 covers other indirect emissions across the value chain. For many businesses, this is the largest and most complex category. It can include purchased goods and services, capital goods, transportation, employee commuting, business travel, waste, leased assets, product use, and end-of-life treatment.
Your reporting period should usually align with your financial year. If your company operates multiple sites, create a complete site list first. Missing a warehouse, temporary office, leased facility, or fleet arrangement can distort the baseline before calculations even begin.
How to calculate scope emissions: the core formula
Most greenhouse gas calculations follow a simple formula:
Activity data × emission factor = greenhouse gas emissions
Activity data is the measurable activity that creates emissions. It might be liters of gasoline, kilowatt-hours of electricity, kilograms of refrigerant, miles traveled, tons of purchased material, or dollars spent with a supplier.
An emission factor converts that activity into carbon dioxide equivalent, commonly written as CO2e. CO2e combines carbon dioxide with other greenhouse gases, such as methane and refrigerants, according to their warming impact. This gives the business one comparable unit for tracking and prioritizing emissions.
For example, if a delivery fleet uses 12,000 liters of diesel in a year, multiply that fuel volume by the relevant diesel emission factor. The resulting CO2e figure is the fleet’s Scope 1 emissions. The same logic applies to electricity: multiply annual kilowatt-hours by the appropriate electricity emission factor to estimate Scope 2 emissions.
The calculation is straightforward. The discipline lies in choosing reliable activity data, using emission factors appropriate to the location and reporting period, documenting assumptions, and applying the same method consistently.
Calculate Scope 1 from fuel and refrigerants
Scope 1 data generally comes from records already held by finance, facilities, operations, or fleet management. Fuel purchase invoices, tank readings, generator logs, vehicle fuel-card reports, and maintenance records are useful starting points.
For stationary combustion, calculate each fuel separately. Natural gas, diesel, gasoline, liquefied petroleum gas, and coal have different factors. Do not combine their volumes before conversion. For mobile combustion, separate fuel used in company-owned or controlled cars, vans, trucks, forklifts, and other equipment.
Refrigerants deserve special attention because small leaks can have a material climate impact. Use maintenance records to identify the refrigerant type and quantity added during servicing. The correct factor depends on the specific gas, not simply the weight of the refill. If records are incomplete, document the estimation method and establish a better leak-tracking process for the next reporting cycle.
Calculate Scope 2 from purchased energy
Gather electricity bills for every included site and record total consumption in kilowatt-hours. Where bills show costs but not usage, request interval or consumption data from the utility or landlord. Cost alone is a weaker basis for calculating emissions because tariffs can change without any change in energy consumption.
Many organizations report Scope 2 using a location-based method, which reflects the average emissions intensity of the local electricity grid. Some may also use a market-based method when they have qualifying contractual instruments, such as renewable energy certificates or a documented green electricity tariff.
These methods answer different questions. Location-based reporting shows the emissions profile of the grid where your facilities operate. Market-based reporting reflects specific purchasing choices. If you report both, explain the difference clearly and retain evidence for any renewable electricity claim. Buying a green product without appropriate documentation should not automatically be treated as zero-emission electricity.
Build Scope 3 calculations in manageable stages
Scope 3 does not need to become an endless data exercise. Begin with a screening assessment to identify categories likely to be material based on spending, operational scale, supplier types, logistics, and product lifecycle. A professional services company may find business travel, commuting, purchased IT equipment, and office energy most relevant. A manufacturer may see purchased materials, freight, waste, and product use dominate.
For purchased goods and services, there are several methods. Supplier-specific data is usually the most informative, especially when a strategic supplier can provide product-level emissions information. Where that is not available, use activity-based data such as kilograms of material purchased, or spend-based estimates using recognized economic emission factors.
Spend-based methods are useful for an initial baseline, but they are less precise. A $100,000 purchase can represent very different physical quantities and emissions depending on market prices, product quality, and geography. As the program matures, replace high-impact spend-based estimates with supplier data or physical activity data.
For business travel, obtain distances and travel class from travel systems, then apply transport-specific factors. For employee commuting, a short survey can capture travel modes, distances, work-from-home patterns, and attendance frequency. For upstream transportation, use shipment weight, distance, and transport mode whenever possible rather than relying only on freight costs.
Create a calculation file that can be checked
A credible inventory is traceable. For each calculation, maintain a clear record of the source document, activity unit, emission factor source, factor year, calculation method, conversion steps, owner, and any assumption made. This is essential for internal review, future assurance, and year-over-year comparisons.
Assign data owners across the business rather than leaving sustainability staff to chase every invoice. Finance can support fuel and procurement data. Facilities can own utility and refrigerant records. Operations can validate production, logistics, and waste information. Procurement can engage priority suppliers. This shared ownership turns emissions management into an operating discipline.
Quality checks should look for obvious gaps: a site with no electricity data, a fleet with fuel costs but no fuel volume, sharp changes from the prior year, duplicate invoices, or mismatched units. Convert units carefully. Gallons, liters, kilowatt-hours, megawatt-hours, miles, kilometers, pounds, and metric tons should never be mixed without documented conversion.
Use the result to prioritize action
The most valuable output is not the total emissions number. It is the hotspot analysis that follows. If purchased materials account for most emissions, focus on specifications, supplier engagement, recycled content, product design, and sourcing decisions. If electricity is the major source, assess energy efficiency, equipment upgrades, operational controls, and renewable energy options. If fleet fuel is material, investigate route planning, vehicle utilization, maintenance, driver behavior, and fleet transition plans.
Set a baseline year only after the calculation approach is stable enough to repeat. Then track both absolute emissions and intensity metrics, such as emissions per unit produced, per revenue dollar, per employee, or per square foot. Absolute emissions show total climate impact. Intensity measures can show whether operations are becoming more efficient as the business grows. Both matter, and neither should be used to hide the other.
A structured ESG implementation pathway can help connect this work to governance, operational improvement, and commercial priorities. Programs such as ESGgen’s ASSA approach are designed to move businesses from awareness and assessment into strategy, implementation, assurance, and continuous improvement.
Your first inventory will contain estimates. That is normal. What creates confidence is being transparent about those estimates, strengthening the data behind material categories, and using each reporting cycle to make better business decisions. Start with the records you have, define ownership, and let the numbers point to the operational changes that can create lasting value.